
A Roth IRA wins for retirement accumulation in almost every case. Full stop. Permanent life insurance is an insurance product first, and its cash-value growth is a distant second job. The Roth IRA lets you shelter $7,500 in 2026, tax-free at withdrawal, while permanent life insurance has no IRS contribution cap but risks becoming a Modified Endowment Contract if you fund it too aggressively. Life insurance earns its place for estate liquidity, high earners who've maxed out other accounts, and legacy planning, not as a Roth substitute.
TL;DR:
- Roth IRAs are primarily designed for tax-free retirement growth, with an annual contribution limit of $7,500 in 2026, while permanent life insurance has no cap but is mainly for estate liquidity and legacy planning.
- Market participation in a Roth IRA typically outperforms cash value growth in a life insurance policy over 20 to 30 years due to higher expected returns and lower fees.
- Cash value in a permanent policy usually takes 10 to 15 years to accumulate meaningfully, and early surrender charges can significantly reduce accessible cash if canceled within the first decade or two.
- Tax rules favor Roth IRAs for flexible withdrawals and no required minimum distributions, whereas life insurance benefits are generally paid income-tax-free, with options for estate tax strategies like ILITs.
- Permanent life insurance makes sense only in specific situations, such as estate tax exposure, maxed-out tax-advantaged accounts, or the need for guaranteed liquidity, not as a primary retirement savings tool.
Table of Contents
- Life Insurance vs Roth IRA: Key Differences at a Glance
- How Does a Roth IRA Actually Work?
- How Does Cash-Value Life Insurance Work?
- Tax Rules and Estate Treatment That Actually Change Your Outcome
- The Real Cost of Choosing Insurance Over a Roth IRA
- When Does Permanent Life Insurance Actually Make Sense?
- Roth IRA or Life Insurance? A Decision Framework You Can Actually Use
- Using a Roth IRA and Life Insurance Together
- Who's Behind This Comparison
- An Honest Take on the Roth vs. Life Insurance Debate
- How Family Guard Life and Health Can Help You Plan Both
- Sources
- FAQ
Life Insurance vs Roth IRA: Key Differences at a Glance
The two products don't compete on the same field, even though salespeople sometimes pitch them as interchangeable. One is a tax-advantaged brokerage account with a government-set contribution ceiling. The other is a death benefit contract that happens to build cash value as a byproduct of how premiums get invested.
Here's how they stack up on the factors that actually decide outcomes:
- Primary purpose: A Roth IRA exists to grow retirement savings tax-free. Cash-value life insurance exists to pay a death benefit, with savings as a secondary feature.
- Who it fits: Roths suit almost anyone with earned income and a tax bill in retirement. Permanent life insurance fits high earners, business owners, and people with estate tax exposure or dependents who need guaranteed liquidity.
- Cost and fees: Roth IRA accounts held at a brokerage typically charge near-zero account fees plus the expense ratio of whatever funds you pick, often under 0.1% for an index fund. Permanent life insurance carries mortality charges, administrative fees, and commissions that eat most of your first-year premium.
- Liquidity and access: Roth contributions come out anytime, tax-free and penalty-free. Cash value in a life policy is accessed through loans or withdrawals, and early surrender usually triggers a charge.
- Tax at distribution and at death: Qualified Roth withdrawals are tax-free. Life insurance death benefits are generally income-tax-free too, but policy loans and withdrawals carry their own tax traps if the policy lapses.
- Time to build value: A Roth invested in the market can compound meaningfully within a decade. A cash-value policy often needs 10 to 15 years before the cash value catches up to what you've paid in.
The 2026 Roth IRA contribution limit sits at $7,500, a hard ceiling that shapes how fast you can build tax-free savings there. Life insurance has no such cap on premium size, which sounds like an advantage until you realize that overfunding it just makes it more expensive insurance, not a better investment.
For pure retirement accumulation, the Roth usually wins. For legacy and estate liquidity, life insurance does a job the Roth can't.
How Does a Roth IRA Actually Work?
You fund a Roth IRA with after-tax dollars, meaning you get no upfront deduction, but qualified withdrawals in retirement come out completely tax-free. That single mechanic is why Investopedia and most financial planners point to Roth IRAs as the default retirement accumulation vehicle for anyone who expects to be in the same or a higher tax bracket later.
The 2026 contribution limit is $7,500 per year for those under 50, with a catch-up amount for savers 50 and older. Income phase-outs apply. Once your modified adjusted gross income crosses certain thresholds, your ability to contribute directly shrinks and eventually disappears, which is why high earners often use a backdoor Roth conversion instead, contributing to a traditional IRA and converting it shortly after.
Statistic to know: A single savings choice with a $7,500 annual ceiling can still produce six figures over two decades of consistent investing, depending entirely on market performance and how early you start.
Withdrawal ordering matters more than most people realize. The IRS treats your contributions as coming out first, tax-free and penalty-free at any age, because you already paid tax on that money. Earnings are a different story. Those become tax-free only as a qualified distribution, meaning you're at least 59½ and the account has been open five years. Pull earnings out early without meeting an exception (first home purchase, certain medical expenses, disability), and you'll owe income tax plus a 10% penalty on that portion.
What makes the Roth attractive:
- Low cost. Most brokerages charge nothing to open or maintain the account.
- Full investment flexibility. You choose stocks, bonds, ETFs, or index funds rather than accepting whatever the insurance carrier's separate account offers.
- Historically strong growth potential, since your money participates directly in market returns rather than a capped, fee-laden crediting rate.
What limits it:
- The $7,500 annual cap means you can't shelter unlimited amounts the way you technically can inside a permanent life policy.
- You're waiting on market growth. There's no guaranteed floor, so a bad decade before retirement can hurt if you haven't diversified by age.
None of that changes the core verdict: for someone building retirement wealth from scratch, the Roth's combination of low cost and tax-free growth is hard to beat with any insurance product.
How Does Cash-Value Life Insurance Work?
Cash-value life insurance is a death benefit contract with a savings account bolted on, not the other way around. Every premium dollar gets split three ways: a portion covers the mortality charge (the actual cost of insuring you), a portion covers administrative fees and commissions, and whatever's left gets credited to the policy's cash value. In the first several years, that leftover portion is small, which is why cash value often stays negligible for the first five to fifteen years of a policy's life.
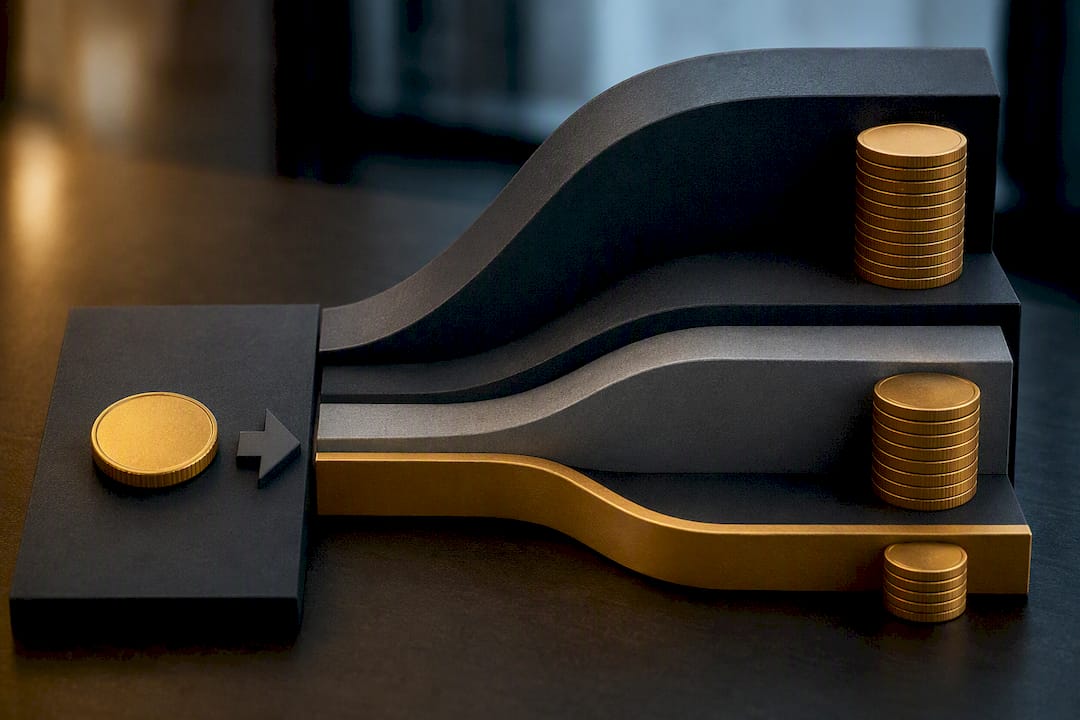
That front-loading is structural, not a sign of a bad policy. Insurance carriers pay agent commissions upfront, and mortality costs rise as you age, so the early years are the most expensive relative to what actually builds cash value.
Once cash value accumulates, you have two ways to access it: loans and withdrawals. A policy loan against cash value is generally income-tax-free while the policy stays in force, but it accrues interest and reduces the death benefit if you don't pay it back. Withdrawals up to your basis (what you've paid in premiums) also come out tax-free, but anything beyond basis is taxed as ordinary income.
Surrender the policy early, and you'll likely face a surrender charge, a fee designed to recoup the carrier's upfront costs. Surrender schedules commonly run 10 to 15 years, declining gradually. Cancel a policy in year three, and you might get back far less than you've paid in.
Pro Tip: Ask any agent pitching a cash-value policy for the exact surrender charge schedule in writing, year by year. If they hesitate or say it "depends," walk away from that specific design until you see the numbers.
There's one more trap worth understanding: the Modified Endowment Contract, defined under IRC 7702A. If you overfund a policy beyond IRS limits relative to its death benefit, it loses its favorable tax treatment. Loans and withdrawals from an MEC get taxed on a last-in-first-out basis, meaning gains come out first and get taxed as income, plus a possible 10% penalty if you're under 59½. The rule exists specifically to stop people from using life insurance as an unlimited tax shelter.
A few operational realities worth flagging before anyone commits:
- Underwriting takes time and depends on health, so a diagnosis later in life can shut the door on getting a new policy.
- Meaningful cash value takes a long runway. If you might need the money within a decade, this isn't the tool.
- Once you're locked in, changing your mind is expensive. Surrender charges and lost time both work against you.
Cash-value life insurance isn't a bad product. It's just a different tool solving a different problem than retirement accumulation.
Tax Rules and Estate Treatment That Actually Change Your Outcome
The tax mechanics here decide who inherits what, and how fast. Get this part wrong, and the difference shows up as thousands of dollars your heirs never see.
A Roth IRA's qualified withdrawals are tax-free to you during retirement, and critically, there are no required minimum distributions during your lifetime. That's a meaningful edge over a traditional IRA, where RMDs force you to start withdrawing (and paying tax) at a set age whether you need the money or not.
When you die, though, your Roth doesn't stay tax-free forever for your heirs. Since the SECURE Act, most non-spouse beneficiaries must empty an inherited Roth IRA within 10 years. The growth inside stays tax-free, but the account can't be stretched across a beneficiary's lifetime the way older rules once allowed.
Life insurance handles death differently. The death benefit is generally paid to beneficiaries income-tax-free, in a lump sum, immediately upon proof of death, no 10-year clock attached. That speed and certainty is exactly why life insurance shows up in estate planning for people with taxable estates or illiquid assets like a business or real estate that can't be sold quickly to cover estate taxes.
Statistic to know: With the Roth IRA capped at $7,500 in annual contributions, an estate needing six or seven figures of immediate liquidity simply can't rely on Roth contributions alone. That gap is exactly where life insurance earns its keep.
For large estates, an Irrevocable Life Insurance Trust (ILIT) can keep the death benefit outside the taxable estate entirely, a strategy that requires coordination with an estate attorney because getting the trust structure wrong defeats the purpose.
Quick comparison of a $500,000 payout in each vehicle:
- Inherited Roth IRA balance: Tax-free growth continues, but the full balance must be withdrawn within 10 years, and heirs manage market risk during that window.
- Life insurance death benefit: Paid immediately, income-tax-free, with no withdrawal deadline and no market risk on the payout itself.
Neither structure is automatically better. A Roth balance keeps growing tax-free for a decade; a death benefit is instant cash with zero uncertainty. Which one matters more depends entirely on what your heirs will actually need and when.
The Real Cost of Choosing Insurance Over a Roth IRA
Run the numbers side by side, and the gap between a Roth IRA and cash-value life insurance stops being theoretical.
Whole life policies typically credit cash value at a guaranteed rate in the 2% to 4% range, sometimes supplemented by non-guaranteed dividends from a mutual insurer. Compare that to historical U.S. stock market returns, which have run considerably higher over long stretches when held in a low-cost index fund inside a Roth. That gap compounds. Over 20 or 30 years, a few percentage points of annual return difference turns into a wealth gap measured in the tens of thousands, sometimes more, depending on contribution size and timing.
Statistic to know: A Roth IRA growing at typical long-term index fund returns can turn a modest annual contribution into a substantially larger balance after two decades than the same dollars would produce inside a whole life policy's guaranteed crediting rate, purely because of the return gap and lower fee drag.
Fees explain most of that gap. A Roth IRA held at a major brokerage often carries no account fee at all, just the expense ratio of the funds you choose, frequently under 0.1% annually for a broad index fund. A cash-value policy carries mortality charges that increase with age, administrative fees, and commissions that can consume most of your first-year premium. None of those costs are optional or negotiable once you've signed the contract.
Here's the scenario that makes the trade-off concrete. Say you're deciding between putting an extra $500 a month into a Roth IRA index fund versus a similarly funded cash-value policy:
- In the Roth, that money participates directly in market growth with minimal drag, compounding at whatever the market returns minus a fraction of a percent in fund fees.
- In the cash-value policy, a chunk of each payment covers insurance costs and commissions before anything reaches your cash value, and what does reach it grows at a guaranteed rate far below typical market returns.
Over 25 years, that difference in starting point and growth rate is not a rounding error. It's the difference between a comfortable retirement supplement and a policy that mostly just paid for insurance you may not have needed in that size.
None of this means whole life is a scam. It means it's priced like insurance, because it is insurance, and insurance costs money to provide guarantees a Roth IRA never makes.
When Does Permanent Life Insurance Actually Make Sense?
Permanent life insurance earns a place in a financial plan under specific, identifiable conditions, not as a general retirement strategy.
- Your estate is large enough to owe estate tax. If your net worth puts you near or above federal estate tax exemption thresholds, a policy held inside an ILIT can provide the cash your heirs need to pay that tax bill without having to sell a business or property under time pressure.
- You've already maxed out every tax-advantaged account available to you. If you're contributing the full $7,500 to your Roth, maximizing your 401(k), and funding an HSA, and you still have surplus income to shelter, permanent life insurance becomes a reasonable next conversation, not a substitute for the accounts you should fill first.
- You need guaranteed liquidity for a dependent with special needs or a business succession plan. A death benefit provides certainty a market-dependent account can't, which matters when a specific dollar amount has to be available on a specific day regardless of market conditions.
- You're locked out of direct Roth contributions by income and don't want the extra step of a backdoor conversion. This is a narrower case, but for some high earners, a well-structured permanent policy plays a supporting role alongside other legacy tools.
Pro Tip: If you're considering life insurance for retirement income (sometimes marketed as a LIRP), get a second opinion from a securities-licensed advisor before signing. Indexed and variable universal life designs carry investment mechanics that are easy to misunderstand, and MEC limits can quietly cap how much you're allowed to fund without losing tax benefits.
Timing matters as much as the reasoning. Insurability only gets harder as you age or develop health conditions, so if permanent insurance genuinely fits your situation, starting earlier locks in better rates and gives cash value more time to overcome those front-loaded early costs. Wait until your 60s to start, and you'll likely pay more for less coverage, with even less runway for cash value to matter.
Roth IRA or Life Insurance? A Decision Framework You Can Actually Use
Before you sign anything, work through these questions in order. Skipping steps is how people end up in a policy that doesn't fit.
Ask yourself:
- What's the goal: retirement income, or leaving money to someone specific?
- What's your time horizon? Under 10 years favors liquidity and low cost. Beyond 20 years opens more options.
- Do you need access to this money before age 59½ without penalty?
- Is your current tax bracket lower than what you expect in retirement?
- Does your estate size create actual tax exposure, or is that a hypothetical someone else raised?
- Are you insurable at a rate that makes permanent coverage cost-effective?
- Have you already maxed your Roth and employer retirement plan?
Action rules that hold up in most situations:
- Fund the Roth IRA first, up to the annual limit, before considering any permanent life insurance for savings purposes.
- If you need life insurance for income replacement, buy term coverage and invest the premium difference rather than a permanent policy, unless a specific estate or legacy need applies.
- Only pursue permanent life insurance for accumulation purposes after you've maxed every other tax-advantaged account and have a defined legacy or liquidity goal in mind.
Red flags that mean stop and verify before signing anything:
- An illustration that assumes aggressive, non-guaranteed dividend growth as if it were certain.
- No clear surrender charge schedule provided in writing.
- First-year commissions that consume most of your premium with little disclosed cash value.
- Funding levels close enough to MEC limits that the agent mentions it as a concern rather than a firm boundary.
If any of those show up in a proposal, pause the conversation and get a second read from an independent source before moving forward.
Using a Roth IRA and Life Insurance Together
These two tools aren't rivals competing for the same dollar. Used correctly, they solve different problems in the same plan.
The typical sequence most advisors recommend looks like this: buy inexpensive term life insurance for pure income replacement protection, max out your Roth IRA and employer retirement plan contributions, and only then consider a targeted permanent policy if a specific legacy or estate need remains. That order keeps costs low while you're building wealth and reserves permanent insurance for the job it actually does well.
Roth conversions deserve a mention here too. Converting traditional IRA or 401(k) funds into a Roth accelerates your tax-free bucket now in exchange for paying tax on the conversion today. That's a different lever than buying life insurance for legacy purposes, and the two aren't mutually exclusive. Some people convert aggressively in lower-income years and still carry a small permanent policy for liquidity certainty their heirs can count on regardless of market timing.
- Term insurance plus max Roth contributions covers most working-age households completely.
- Roth conversions make sense when you expect higher future tax rates or want to reduce future RMD exposure on a traditional account.
- Bring in a securities-licensed advisor or estate attorney once you're discussing ILITs, variable universal life designs, or conversions large enough to shift your current tax bracket.
That last step matters more than people expect. Structuring a permanent policy for legacy purposes, or converting a large traditional balance, has enough moving parts that a specialist earns their fee.
Who's Behind This Comparison
An independent agency offers health and life insurance, annuities, Medicare supplement plans, dental and vision coverage, and retirement income planning in multiple states. Insurance licensing is state-specific, so what's available to you depends on where you live.
The agency also publishes practitioner-level breakdowns of products like indexed universal life and annuities versus bonds on its blog, aimed at helping readers understand mechanics before they sit down with any agent, including one from Family Guard Life and Health.
Nothing here replaces personalized advice. Contribution limits, tax brackets, insurability, and state availability all shift the right answer for your specific situation, so treat this as a framework for the conversation, not a substitute for a licensed quote and a look at your actual numbers.
An Honest Take on the Roth vs. Life Insurance Debate
The insurance industry has spent decades trying to convince people that permanent life insurance is a retirement plan. It isn't, and the math in this article shows exactly why: guaranteed crediting rates in the low single digits can't compete with direct market participation over 20 or 30 years, and the front-loaded costs of a permanent policy make the first decade brutal for anyone hoping to build accessible cash value.
That doesn't mean permanent insurance is a bad product, and it doesn't mean every agent pushing it is doing you a disservice. The mistake is treating it as an either-or decision instead of a sequencing question. Fund your Roth first because nothing else offers tax-free growth at that price point. Layer in permanent insurance later, and only when a specific need, an estate tax exposure, a business succession plan, a dependent who needs guaranteed liquidity, actually justifies the cost.
If you take one thing from this: run your own projection before you sign anything, and get a straight answer on insurability and surrender terms before you assume a policy fits your plan.
— Shereka
How Family Guard Life and Health Can Help You Plan Both
Deciding between a Roth IRA and permanent life insurance isn't a one-size-fits-all call, and it shouldn't be made from a generic illustration alone. An independent agency works without ties to any single insurance carrier, providing recommendations based on clients' actual numbers.
The agency offers retirement income planning built around your specific timeline, tax situation, and legacy goals, alongside term, whole, and universal life insurance for readers who've confirmed a real need for permanent coverage. If estate liquidity or legacy planning is part of the conversation, resources like Golden Memorial can help with related end-of-life planning needs as well. Every recommendation depends on your income, health, existing accounts, and goals, so the next real step is a personalized conversation. Start by requesting a retirement income projection through Family Guard Life and Health and find out, with real numbers, whether your plan needs a Roth, a policy, or both.
Sources
- Investopedia — Roth IRA
- LegalClarity — Cash value life insurance vs Roth IRA: pros and cons
- U.S. News — Life insurance vs Roth IRA
FAQ
Why Does Dave Ramsey Say No to Whole Life Insurance?
Dave Ramsey's core objection is cost and return. Whole life bundles an expensive insurance product with a low guaranteed crediting rate, typically 2% to 4%, far below what a low-cost index fund inside a Roth IRA has historically returned over the long run. His preferred approach is cheap term coverage plus investing the difference directly.
How Much Does a $100,000 Life Insurance Policy Cost a Month?
Cost depends heavily on age, health, and whether the policy is term or permanent. Term coverage for that amount is generally inexpensive for younger, healthy applicants, while a permanent policy with the same death benefit costs substantially more because part of the premium builds cash value on top of the insurance cost. Getting an exact quote requires underwriting, which you can request through a life insurance quote with Family Guard Life and Health.
How Much Will $10,000 in a Roth IRA Be Worth in 20 Years?
The outcome depends entirely on investment choice and market performance, since a Roth has no guaranteed growth rate. Based on historical long-term stock market returns, money invested in a diversified index fund inside a Roth has historically grown substantially over two decades, though past performance never guarantees future results.
What Does Dave Ramsey Say About Roth IRAs?
Ramsey consistently recommends Roth IRAs as a primary retirement savings tool because of their tax-free growth and withdrawal rules. He typically pairs that advice with maxing out the annual contribution limit before considering any insurance-based savings product.
Can I Have Both a Roth IRA and Life Insurance?
Yes, and for many households that's the right structure. A Roth IRA handles retirement accumulation while term or permanent life insurance covers protection or legacy needs, and the two work together rather than competing for the same dollar.