
A stretch IRA annuity is a tax strategy that lets beneficiaries extend inherited retirement distributions over their lifetime, spreading taxable income and preserving tax deferral far beyond the original owner's death. The stretch IRA annuity rules explained here reflect the current legal landscape shaped by the SECURE Act, which fundamentally changed how most beneficiaries must handle inherited accounts. Knowing these rules before you pass assets to heirs, or before you inherit them yourself, can mean the difference between a manageable tax bill and a costly surprise. Familyguardlh works with clients across 22 states to build retirement income plans that account for exactly these rules.
What are the current stretch IRA rules under the SECURE Act?
The SECURE Act replaced the old lifetime stretch with a strict 10-year depletion rule for most non-spouse beneficiaries. Any beneficiary who inherits an IRA from an owner who died after january 1, 2020 must withdraw the entire balance by the end of the tenth year after the owner's death. That compressed window pushes large taxable distributions into a shorter period, which often bumps beneficiaries into higher tax brackets.
Not every beneficiary faces the 10-year rule. The IRS created a category called Eligible Designated Beneficiaries, or EDBs, who can still stretch distributions over their own life expectancy. EDBs include:
- Surviving spouses
- Minor children of the account owner (until they reach the age of majority)
- Disabled individuals under IRS definitions
- Chronically ill individuals
- Beneficiaries not more than 10 years younger than the deceased owner
Spouses who inherit IRAs have the most flexibility of any beneficiary type. A surviving spouse can roll the inherited IRA into their own account and defer required minimum distributions (RMDs) until age 73. That option preserves the lifetime stretch in practical terms, even after the SECURE Act.
The RMD picture gets more complicated when the original owner had already started taking distributions before death. Beneficiaries must continue annual RMDs during years 1 through 9 under the 10-year rule if the owner died after their required beginning date. Skipping those annual withdrawals triggers excise taxes on top of the 10-year deadline pressure.
Roth IRAs follow the same 10-year rule for non-spouse beneficiaries, but qualified distributions from Roth accounts remain income tax free. That distinction makes Roth IRAs especially valuable as inherited assets.
Pro Tip: Name a contingent beneficiary on every IRA and annuity contract. If your primary beneficiary predeceases you and no contingent is named, the account may pass through your estate and lose all stretch options entirely.
How do stretch annuities work, and what is the difference between qualified and non-qualified contracts?
A stretch annuity is a distribution option offered by some annuity contracts that allows a beneficiary to receive payments over their life expectancy rather than in a lump sum. The term "stretch annuity" is an industry shorthand. The formal mechanism is a life expectancy payout election within the annuity contract itself.
The distinction between qualified and non-qualified annuities drives nearly every tax outcome for beneficiaries.
| Feature | Qualified annuity | Non-qualified annuity |
|---|---|---|
| Funding source | Pre-tax dollars (IRA, 401k) | After-tax dollars |
| Tax on distributions | 100% taxable as ordinary income | Only earnings portion is taxable |
| SECURE Act 10-year rule | Applies to most non-spouse beneficiaries | Does not apply; governed by contract terms |
| Stretch availability | Limited by SECURE Act rules | Available if contract allows it |
| Default payout if no election | Follows IRS inherited IRA rules | Often 5-year rule under IRC Section 72(s) |
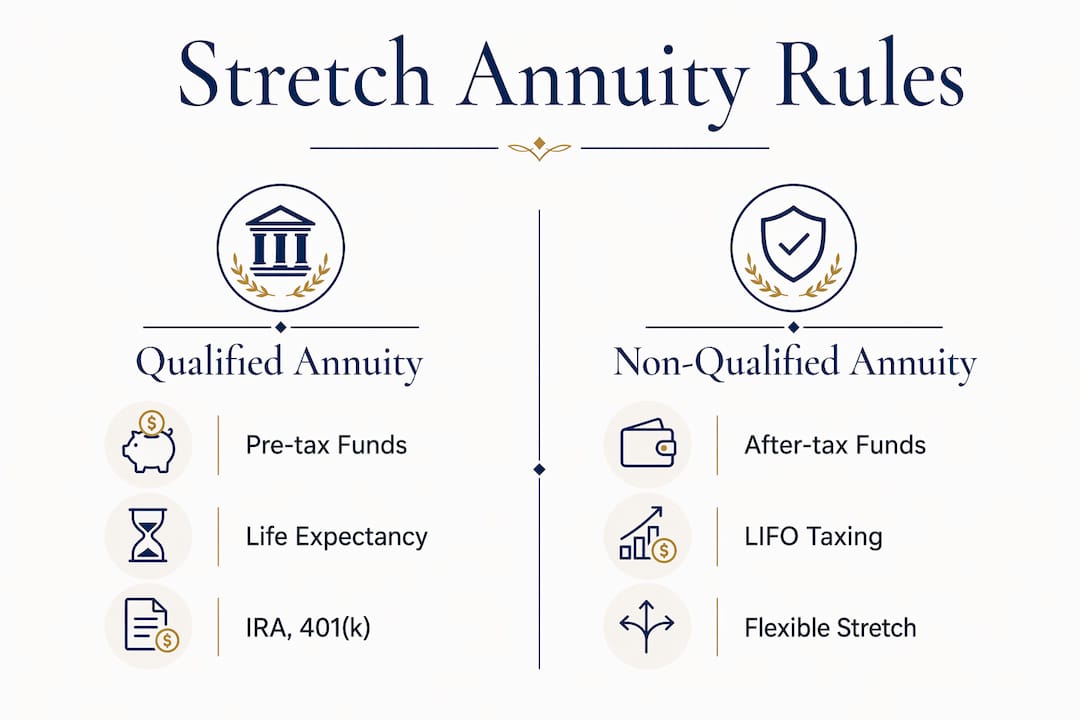
Non-qualified annuities still allow stretch options where beneficiaries may take distributions over their life expectancy to defer income recognition. This is a significant advantage over qualified accounts post-SECURE Act. A beneficiary who inherits a non-qualified annuity can spread taxable income over decades rather than 10 years, which keeps annual tax bills lower.
The IRS taxes non-qualified annuity withdrawals using the LIFO method, meaning earnings come out first and are taxed as ordinary income before any return of principal. Once a beneficiary annuitizes the contract, the insurer applies an exclusion ratio to each payment, splitting it between taxable gain and tax-free return of basis. That ratio is calculated based on the total investment in the contract divided by the expected total payout.
Election deadlines are strict. Beneficiaries who fail to elect the life expectancy payout within one year of the owner's death typically default to a 5-year distribution schedule. That default accelerates income recognition and can significantly increase the tax burden in a short window.
Pro Tip: Request the annuity contract's beneficiary payout provisions in writing immediately after inheriting any annuity. Insurers are not required to proactively explain your stretch election deadline.
What are the tax implications and penalties for missing stretch IRA annuity requirements?
Tax exposure on inherited retirement assets is higher than most beneficiaries expect. Every dollar distributed from a qualified IRA or qualified annuity counts as ordinary income in the year received. There is no capital gains treatment, no step-up in basis, and no special rate for long-term holding. A beneficiary who withdraws a large inherited IRA in a single year can easily push their effective tax rate well above what they would pay with a stretched distribution schedule.
Annuity gains are taxable as ordinary income when distributed, regardless of how long the contract was held. This is a point that catches many beneficiaries off guard. Stocks and real estate often receive favorable capital gains treatment or a step-up in basis at death. Annuities receive neither.
A common and costly misconception is that annuities receive a step-up in basis at death. They do not. The full gain above the original investment remains taxable when distributed, which makes the stretch option even more valuable as a way to spread that liability over time.
Penalties for missed RMDs are severe:
- A 25% excise tax applies to any missed RMD amount in the year it was due.
- That penalty drops to 10% if the beneficiary corrects the missed distribution within two years.
- The IRS penalty waiver period that covered 2021 through 2024 has ended as of 2026. No further grace periods are currently in effect.
- Beneficiaries under age 59½ who take distributions from inherited non-qualified annuities may also owe a 10% early withdrawal penalty on the earnings portion, depending on the contract structure.
Section 1035 exchanges offer a way out when an inherited annuity contract lacks stretch provisions. This IRS provision allows a tax-free transfer of the annuity contract to a new insurer whose contract does include life expectancy payout options. The exchange preserves the original cost basis and defers taxes while restoring control over distribution timing. Not every situation qualifies, and the rules around inherited contract exchanges are narrow, so professional review is necessary before initiating one.
What practical steps optimize the use of stretch IRA annuity rules for estate planning?
Getting the most from an IRA stretch strategy requires action before and immediately after the account owner's death. Waiting too long eliminates most options.
-
Review every annuity contract now. Not all annuity contracts include stretch provisions. Contract language and insurer policies govern stretch eligibility and election deadlines. Ask your insurer directly whether life expectancy payouts are available to beneficiaries and what the election window is.
-
Update beneficiary designations regularly. The IRA stretch strategy only works if the right beneficiaries are named. Spouses, EDBs, and non-EDBs face completely different rules. Naming a trust as beneficiary can complicate or eliminate stretch options unless the trust is drafted specifically to qualify.
-
Act within one year of the owner's death. Beneficiaries must elect the stretch option within one year of the owner's death to avoid defaulting to a 5-year schedule. That deadline passes quickly during a period of grief and estate administration. Put the election on a calendar immediately.
-
Name successor beneficiaries. Successor beneficiaries may continue distributions based on the first beneficiary's IRS life expectancy table. Without a named successor, the remaining balance may be paid out in a lump sum to the estate, triggering a large taxable event.
-
Evaluate the spousal rollover carefully. Surviving spouses who treat an inherited IRA as their own can defer RMDs until age 73 and avoid early withdrawal penalties before age 59½. However, a spouse who needs income before age 59½ may be better served by keeping the account as an inherited IRA temporarily, since inherited IRA distributions are not subject to the 10% early withdrawal penalty.
-
Work with a licensed advisor before making any election. The NAIC best interest standard, in place since 2020, requires that annuity recommendations prioritize your interests. Use that standard as a baseline expectation when evaluating any advisor's guidance on inherited annuity elections.
Pro Tip: If you inherit a non-qualified annuity and the contract lacks stretch provisions, ask about a Section 1035 exchange to a contract that does. Time is limited, but the tax savings over a lifetime payout can be substantial.
Key takeaways
The most effective IRA stretch strategy after the SECURE Act requires knowing which beneficiary category applies, electing the right payout option within the required deadline, and reviewing every annuity contract for stretch eligibility before a death occurs.
| Point | Details |
|---|---|
| SECURE Act 10-year rule | Most non-spouse beneficiaries must deplete inherited IRAs within 10 years of the owner's death. |
| Eligible designated beneficiaries | Spouses, disabled individuals, and certain others can still stretch distributions over their life expectancy. |
| Election deadlines are firm | Beneficiaries must elect life expectancy payouts within one year of death or default to a 5-year schedule. |
| Missed RMDs carry steep penalties | A 25% excise tax applies to missed distributions, dropping to 10% only if corrected within two years. |
| Section 1035 exchanges restore options | A tax-free contract transfer can move an inherited annuity to one with stretch provisions when the original lacks them. |
What I have learned about stretch IRA annuities after years of retirement planning
The SECURE Act did not kill the stretch strategy. It narrowed it significantly for qualified accounts, but non-qualified annuities remain one of the few vehicles where a beneficiary can still spread distributions over a lifetime. That distinction gets lost in most conversations about inherited retirement assets, and it costs families real money.
The biggest planning failure I see is not the tax math. It is the timing. Families lose the stretch option not because they chose the wrong strategy, but because they missed a one-year election deadline while managing grief, probate, and estate paperwork simultaneously. The insurer does not send a reminder. The IRS does not send a warning. The deadline simply passes.
The second failure is the step-up-in-basis myth. People assume annuities work like stocks at death. They do not. That misunderstanding leads beneficiaries to delay distributions thinking they are protecting themselves, when in reality they are just compressing a larger taxable event into fewer years.
My honest advice: treat the annuity contract review and beneficiary election as a financial emergency in the first 30 days after a loved one's death. Everything else in the estate can wait longer than that deadline can.
— Shereka
Retirement income planning with Familyguardlh
Stretch IRA annuity rules are detailed, and the cost of a missed deadline or wrong election can follow a family for years. Familyguardlh specializes in retirement income planning for clients across 22 states, including annuity selection, beneficiary strategy, and guidance on how inherited assets fit into a broader retirement income plan.
Whether you are setting up your own annuity with beneficiaries in mind or you have recently inherited a retirement account, Familyguardlh can help you understand your options before a deadline closes them. Licensed in Arizona, Florida, Texas, Georgia, Michigan, and 17 additional states, the team brings real-world knowledge of annuity contracts and IRS distribution rules to every client conversation. Reach out to Familyguardlh to schedule a retirement income review.
FAQ
What is a stretch IRA annuity?
A stretch IRA annuity is a distribution strategy that allows a beneficiary to receive inherited retirement or annuity payments over their life expectancy rather than in a lump sum, spreading taxable income over time.
Did the SECURE Act eliminate the stretch IRA?
The SECURE Act eliminated the lifetime stretch for most non-spouse beneficiaries of qualified IRAs, replacing it with a 10-year depletion rule for deaths after january 1, 2020. Eligible designated beneficiaries, including spouses, can still use life expectancy payouts.
How long does a beneficiary have to elect the stretch option on an annuity?
Most annuity contracts require the beneficiary to elect the life expectancy payout within one year of the owner's death. Missing that window typically defaults the contract to a 5-year distribution schedule.
What happens if I miss an RMD on an inherited IRA?
A missed RMD triggers a 25% excise tax on the amount that should have been withdrawn. That penalty drops to 10% if the beneficiary corrects the shortfall within two years of the missed distribution.
Can a Section 1035 exchange help if my inherited annuity has no stretch option?
A Section 1035 exchange can transfer an inherited annuity contract to a new insurer whose contract includes life expectancy payout provisions, preserving tax deferral and restoring distribution flexibility under IRS rules.